Four Things Every HOA Board Should Do Before Budget Season
Budget season has a way of sneaking up on boards. One week it is summer, and the next the calendar is turning toward fall and someone realizes the budget needs to be finalized before the new year. The boards that navigate this well are the ones that do a few specific things before they sit down to set the numbers. Here are four of them.
Pull Your Comparative Income and Expense Report
Before you touch next year’s budget, you need to understand how this year actually went. Not your best guess at it. The actual numbers, line by line, compared against what you budgeted.
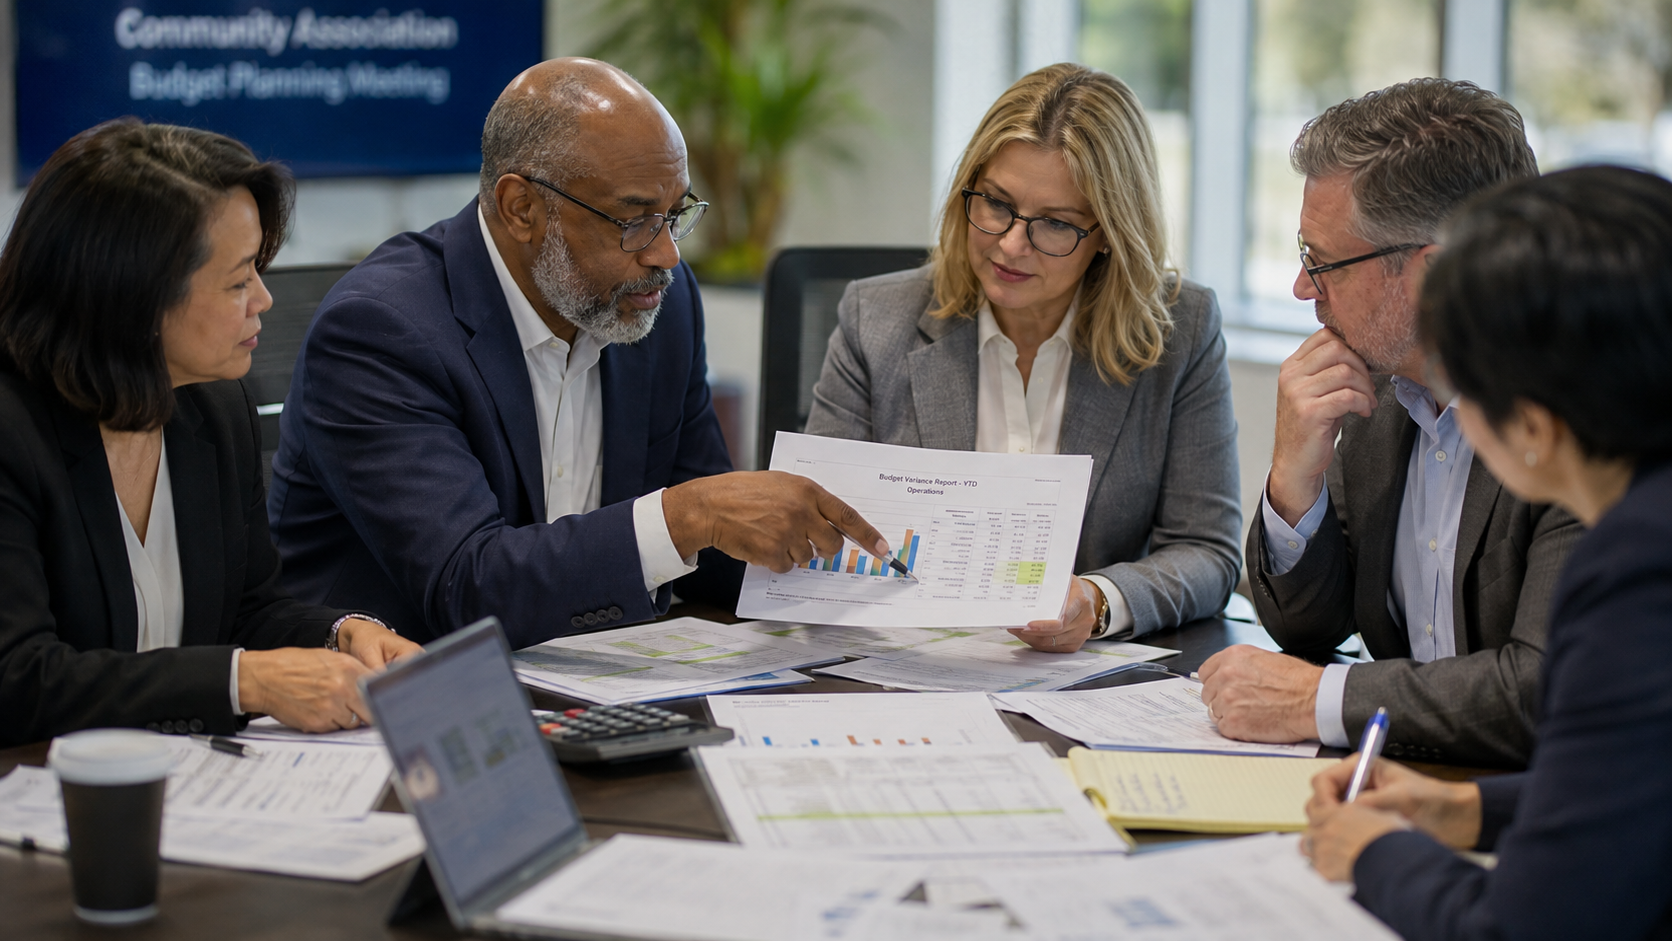
The report to pull is the comparative income and expense report. It shows three things side by side for each line item: what you actually spent, what you budgeted, and the variance between the two, for both the current month and year to date. The variance column is where the real information lives. Every line item with a significant variance is a conversation you need to have before you set next year’s budget. If landscaping ran 30% over budget this year, you cannot set the same landscaping number next year and expect a different result.
If you are not currently receiving this report as part of your monthly financial packet, ask for it. It is the single most useful tool for understanding where your budget stood and what needs to change.
Review Your Delinquency Report
Your budget is built on the assumption that assessment income is coming in every month. Your delinquency report tells you whether that assumption is actually true.
Before you finalize your budget, look at the current delinquency picture. The report shows how much each homeowner owes and how old that debt is, broken into 30, 60, and 90-day buckets. If homeowners have been delinquent for 60 days or more and nothing has happened, that is a problem that needs to be addressed before the new year begins. You cannot build a realistic budget around income that is not reliably coming in.
Budget Higher Than You Think You Need To
This is the one boards resist most, and it is the one that costs communities the most when they get it wrong.
Most boards avoid increasing the operating budget because homeowners do not like fee increases. The problem is that holding the line almost always leads to a special assessment, which homeowners like even less. A small, planned increase that homeowners can prepare for is always better than a surprise assessment mid-year.
Build in a cushion. It covers mid-year price increases from vendors, unexpected repairs, and the other surprises that every community faces in the course of a year. If you end the year under budget, the surplus goes to reserves, which is exactly where it should go. A proper budget gives homeowners the predictable housing costs they signed up for when they joined the community.
Know the True Cost of Your HOA Accounting
Most boards think of accounting as a fixed line item, whatever they are paying their management company or accounting firm. But the true cost is almost always higher than that number suggests. The full picture includes:
- Software fees and banking fees
- Check stock and mailed items
- Hours the treasurer spends on accounting tasks every month
- Hours spent chasing late or incorrect reports
- The cost of correcting errors that should not have happened in the first place
Community Financials has a free cost calculator at communityfinancials.com that shows the full picture. Once you know the true cost, you can make an informed decision about whether your current setup is actually delivering value.
The question is not whether you can afford professional HOA accounting. It is whether you can afford what bad accounting is currently costing you.
These four steps, pulling the right reports, understanding your delinquency picture, budgeting with a cushion, and knowing your true accounting costs, give your board a much clearer foundation going into budget season. Part two covers the reserve and collections steps that protect your community’s long-term financial health.
If you would like to understand how Community Financials can help your board prepare for budget season, we would be glad to have that conversation.
Schedule a consultation or call 833-CONDO-HOA.
Important Disclaimer: This post is for educational purposes only and does not constitute legal, tax, or financial advice. Always consult a qualified attorney and CPA for guidance specific to your community.