How Your HOA’s Landscaping Is Affecting Your Insurance Costs – And What To Do About It
Insurance premiums have been one of the fastest-growing line items in HOA and condo budgets for the past several years. According to a study by ICE Mortgage Technology, premiums rose 70 percent between 2019 and 2025, and for associations dropped by their carriers, the jump was far worse, with many ending up in the excess lines market at double or triple their previous rates. Most boards know costs are up. What fewer boards realize is that one of the most effective ways to manage those costs is already sitting right outside their front door.
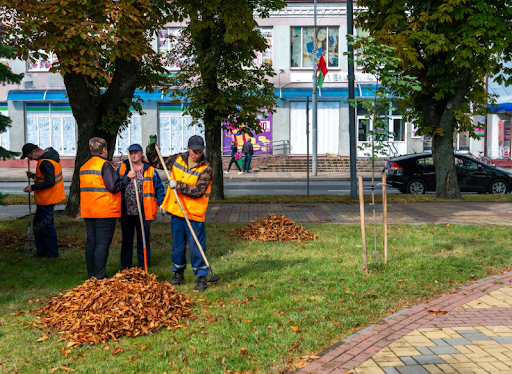
Your community’s landscaping is not just a curb appeal decision. It is a risk management decision. And the choices your board makes about trees, walkways, drainage, and outdoor maintenance could have a direct impact on your insurance premiums, your coverage terms, and your liability exposure.
Why Insurers Pay Attention to Your Landscaping
When an insurance carrier underwrites or renews a policy for a community association, they often look for signs of how well the property is maintained. Landscaping is one of the most visible indicators.
According to a recent CooperatorNews article on HOA landscaping and insurance, neglected landscaping can influence premiums, deductibles, and coverage terms -and in some cases, insurers may require repairs as a condition of maintaining coverage.
A community with overgrown trees, cracked walkways, and poor drainage signals broader maintenance issues that increase risk. Because common areas are the association’s responsibility, boards are often named in the resulting claims or lawsuits even when the hazard seems minor.
The Four Landscaping Risks That Can Drive Insurance Claims
Walkways and hardscaping. Cracked pavement, settling slabs, and root intrusion are among the most common causes of trip and fall claims. Walkways should be constructed with stable, slip-resistant materials and inspected regularly for surface changes. When problems are identified, they should be addressed promptly rather than deferred.
Trees and vegetation. Overgrown vegetation can obstruct lighting, signage, and sightlines for both pedestrians and drivers. Dead or diseased trees pose a particularly high risk during storms when falling branches or uprooted trees can cause serious injury or significant property damage. Routine inspections by qualified arborists are essential to catching risks before they become claims.
Drainage. Poor grading or clogged drainage systems create standing water which increases the risk of slip and falls and can create hazardous ice conditions in colder months. Improper water management can also direct runoff toward foundations or lower level units, resulting in property damage claims. Landscaping should work with natural drainage patterns rather than against them.
Storm preparedness. Severe weather is occurring more frequently and with greater intensity across the country. Associations that inspect trees, secure loose decorative elements, and clear drainage systems before storm season are better positioned to reduce damage and demonstrate responsible maintenance if a claim arises. Tree branches rubbing against siding, roofing, or gutters are also worth watching, as these can cause water intrusion or premature wear over time.
Documentation Is as Important as the Work Itself
One of the most overlooked tools in managing landscaping risk is documentation. Inspection records, maintenance schedules, work orders, and records of corrective actions help demonstrate that the board acted reasonably and responsibly.
If a claim arises, that documentation can make a meaningful difference in how insurers and courts evaluate the association’s conduct.
Landscaping Contractors Add Their Own Layer of Risk
Boards that hire outside landscaping contractors need to understand that the association can still be named in a lawsuit if a contractor causes injury or property damage on the premises. Before hiring any landscaping vendor, boards should verify that the contractor carries appropriate insurance coverage. Contracts should clearly outline responsibility, indemnification, and risk transfer. Even routine maintenance work can result in claims if contractors are not properly vetted.
Questions Worth Asking Before Your Next Insurance Renewal
- When did your community last conduct a professional inspection of trees and walkways?
- Are drainage systems functioning properly and cleared of debris?
- Do your landscaping contracts include proper insurance and indemnification language?
- Are you documenting inspections, maintenance, and corrective actions in a way that would hold up if a claim arose?
- Has your board reviewed landscaping conditions since the last major weather event?
If the answer to any of those is no, addressing them before your next insurance renewal is worth the time and could save your community real money.
What Good Financial Reporting Has to Do With This
Cost controls in any community start with receiving monthly reports that are accurate. When boards have reliable numbers in front of them every month, they can track every budget line item, catch increases early, and make informed decisions before costs get out of hand. That includes insurance, but it applies across the board.
If your board is not getting that level of visibility, it is worth looking at how your financials are being managed. Working with Community Financials means boards not only receive accurate monthly reports but also gain time back by having the accounting handled efficiently in one place.
Schedule a call at CommunityFinancials.com or call 833-CONDO-HOA.
Important Disclaimer: This post is for educational purposes only and does not constitute legal, tax, insurance, or financial advice. Always consult a qualified insurance professional and attorney for guidance specific to your community.